Cantonal elections in Bern: guide to the calendar and voting
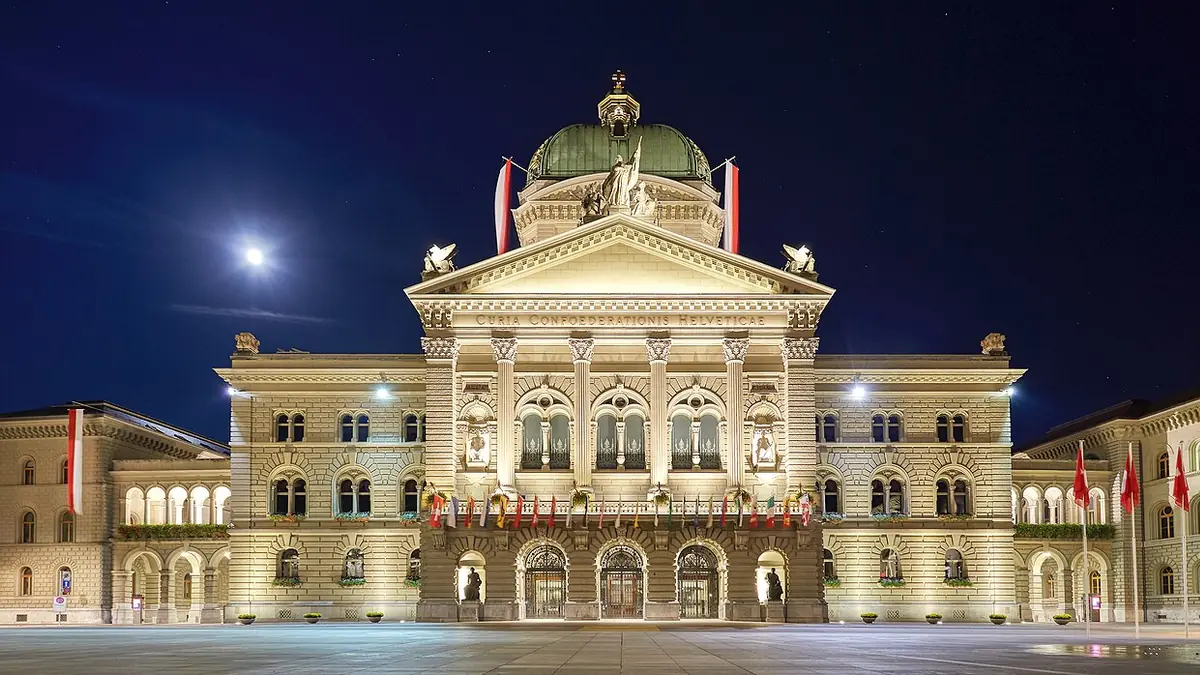
Practical guide to cantonal elections in the Canton of Bern: electoral system, calendar, voting procedures, lists and institutional responsibilities.
Context
TL;DR
- Topic: cantonal elections in the Canton of Bern
- Focus: calendar, voting procedures, lists and official sources
- The cantonal level must be distinguished from the federal and municipal levels
Key facts
- Scope → Canton of Bern
- Subject → cantonal elections
- Information → electoral system, calendar, voting procedures and lists
- Reference → responsible electoral office
- Taxation → direct federal tax, cantonal tax and municipal tax
The guide dedicated to cantonal elections covers the Canton of Bern. The editorial focus brings together the steps needed to navigate: electoral system, calendar, voting procedures, lists and the electoral office responsible for official information. The official source is therefore the starting point for checking the elements of the consultation, without automatically carrying over guidance relating to another canton or another institutional level.
For those who live or work in Switzerland, the distinction matters because taxes, social security, employment, housing and the cost of living do not all fall under the same office. A guide to cantonal voting must therefore distinguish between the federal, cantonal and municipal levels. The calendar and lists relate to the consultation; the authority responsible for a tax or a benefit may instead be different.
The map of responsibilities
The tax system offers the clearest separation. In Switzerland there are three levels: direct federal tax, cantonal tax and municipal tax. Each canton has its own law and its own multiplier; at the municipal level, the multiplier is applied to the cantonal tax. AFC/ESTV oversees direct federal tax and VAT. The cantonal administrations, on the other hand, are responsible for cantonal and municipal taxes. For those preparing the dichiarazione delle imposte, distinguishing these three levels is more useful than reading a single tax rate out of context.
Institutions also have different areas of responsibility. UFAS/BSV deals with social security, including AVS/AI/LPP, but does not set taxes. UST/BFS produces statistics and does not set tax rates. The guide to cantonal voting can be used as a map for locating the correct institutional level: for the calendar, voting procedures, lists and details of the consultation, the responsible electoral office is the reference to follow.
| Scope | Reference |
|---|---|
| Direct federal tax and VAT | AFC/ESTV |
| Cantonal and municipal taxes | cantonal administrations |
| Social security | UFAS/BSV |
| Statistics | UST/BFS |
This grid helps clarify the practical meaning of the cantonal level without confusing it with federal or municipal responsibilities.
Operational details
Practical reading for residents and workers
The practical value of the distinction emerges in everyday expenses: not all items affecting the budget, work or housing fall under the same level of responsibility. A useful reading of the cantonal vote distinguishes matters administered by the cantons and municipalities from federal rules.
Health, services and cost of living
LAMal/KVG is compulsory for residents and must be taken out within three months of arrival. It is private insurance with per-capita premiums: it is neither a tax nor a salary contribution. For adults, the deductibles are CHF 300, 500, 1000, 1500, 2000 and 2500. Premiums depend on the canton and region, while premium reductions are a cantonal subsidy. For the cost of living, it is therefore advisable to separate the premium, deductible and cassa malati from the tax calculation.
Social assistance is generally administered by cantons and municipalities according to need. Motor vehicle taxes, energy incentives, building permits and contributions to continuing education follow cantonal rules and offices. Requirements, deadlines and amounts must be verified using the canton’s official source. The operational point here is to contact the right office, not to transfer a figure from another territory.
Building insurance is compulsory or organized differently depending on the canton. Civil protection is coordinated at cantonal level within the framework of federal law; call-ups and allowances should be verified with the competent authority.
Tenancy law, however, has a common federal basis: CO art. 253 et seq. is the same in every canton. The security deposit may not exceed three months’ rent and must be paid into a blocked account in the tenant’s name. A landlord’s termination notice is valid only on the official cantonal form; any challenge must be submitted to the conciliation authority within 30 days.
Work and payslips
The labor market also requires distinguishing between the federal and cantonal levels. There is no federal minimum wage, although some cantons have their own. The maximum working time is 45 hours per week in industry, offices and retail, or 50 in other sectors. The minimum vacation entitlement is four weeks, or five for those under 20; maternity leave lasts 14 weeks at 80% IPG and paternity leave two weeks. Notice periods are one, two or three months depending on seniority: first year, second to ninth year, and from the tenth year onward.
On a payslip, AVS/AHV and LPP/BVG therefore remain pension-related items to be read separately from the cantonal tax level. The LPP rates on the coordinated salary are 7% between ages 25 and 34, 10% between 35 and 44, 15% between 45 and 54, and 18% from age 55 until the reference age. For more information on AVS and LPP, consult AVS e LPP.
Useful planning tools
To estimate your pension strategy, use the pension planner and the pillar 3 simulator.
Key points
Practical procedure for using the guide
The safest procedure starts from the official source and proceeds by levels, not by assumptions. The Canton of Bern is the geographical point of consultation; the competences listed in the guide refer instead to different offices depending on the subject matter.
Four operational steps
1. Open the communication from the responsible electoral office. Look in the same reference for the electoral system, the calendar, the voting method, and the lists. If a detail does not appear in the official material, do not fill it in with a date or a list from another canton.
2. Classify the question before looking for the answer. For direct federal tax and VAT, the reference is FTA/ESTV; for cantonal and municipal taxes, the cantonal administrations are competent. OASI, IV, and occupational pension plans fall under social security handled by FSIO/BSV, while FSO/BFS deals with statistics.
3. Note the deadlines concerning your personal situation. Those arriving in Switzerland must take out KVG/LAMal health insurance within three months. In rental matters, the dispute must be submitted within 30 days to the conciliation authority; the deposit remains limited to three months and the landlord's termination requires the official cantonal form. For employment, the notice periods are one, two, or three months depending on the seniority indicated by the source.
4. Check the year before using an amount. Updated every year are the Pillar 3a maximum limit, the occupational pension threshold and coordination deduction, the ALV/AC maximum limit, the average KVG/LAMal premiums, and the median salary. If the year is not certain, avoid precise figures and check the official source of the canton or competent authority. To compare the impact on your budget, you can consult the cost of living in Switzerland.
After checking the calendar and jurisdictions, translate the social security and salary items into your net income with the salary calculator.
Frequently Asked Questions
- What are the key information for cantonal elections in Bern?
- The perimeter of the guide is the Canton of Bern and brings together the necessary steps to navigate between the electoral system, calendar, voting methods, lists and the electoral office responsible for official information. It is essential to follow the official source to check the elements of the consultation, without transferring indications referring to other cantons or institutional levels.
- How are tax responsibilities divided in Switzerland?
- In Switzerland, the tax is divided into three levels: direct federal tax, cantonal tax and municipal tax. Each canton has its own law and its own multiplier, while at the municipal level the multiplier is applied on the cantonal one. The AFC/ESTV follows the direct federal tax and VAT, while the cantonal administrations follow the cantonal and municipal taxes.
- What rules apply to tenancy law in Switzerland?
- The lease right has a common federal basis in which the Code of Obligations (CO art. 253 et seq.) is the same in each canton. The security deposit does not exceed three months of rent and must be paid into a restricted account in the tenant's name. The lessor's cancellation is valid only on the official cantonal form and the dispute must be submitted within 30 days to the conciliation authority.
Related articles
- All articles: Agreements and politics
- Elezioni cantonali nel Canton Lucerna: calendario e voto
- Elezioni cantonali a Zurigo: guida a calendario e voto
- Giorni festivi Cantone di Berna: calendario e regole
- Giorni festivi Cantone Zurigo: guida a calendario e regole
- Sistema scolastico del Canton Berna: iscrizione e cicli