Federal votes Switzerland: how cantonal referendums work
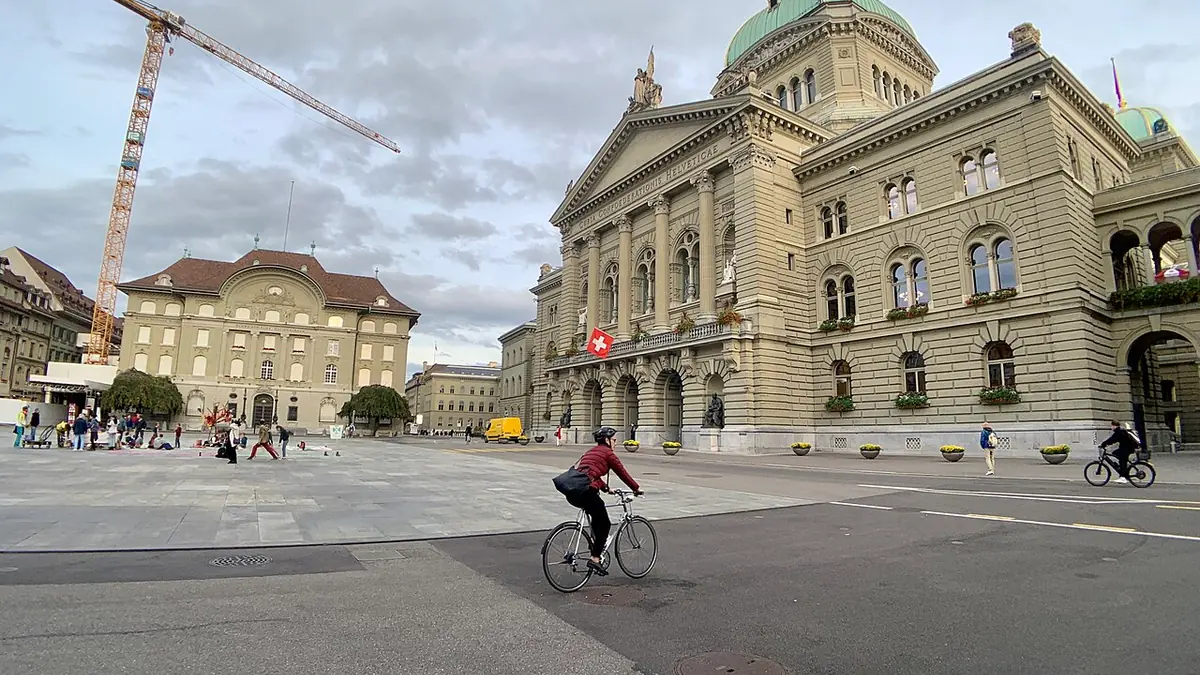
Learn about the rules for federal voting, tax rates, and the 2024 border agreement for cross-border workers.
Context
In a nutshell
- New Frontier Agreement in force from 1 JANUARY 2024 for new frontier workers
- AVS/AI/IPG rates 5.3% employee, AD/AC 1.1% with CHF 148'200 ceiling
- Italian personal income tax 23% up to €28,000, 33% €28,001-50,000, 43% over €50,000
- Old cross-border workers remain taxed only in Switzerland (Art. 9 of the 2020 Agreement).
Key facts
- What: New Border Agreement for Italian border workers in Switzerland
- When: Effective from 1 JANUARY 2024 (signature 23/12/2020)
- Where: Switzerland and Italy, with cantonal application
- Who: Italian border workers working in Switzerland
- The €10,000 threshold in Article 4 of Italian Law No. 83/2023 applies exclusively to employment income earned continuously and exclusively by Italian residents in a foreign border area or neighbouring country, as referred to in Article 1(175) of Law No. 147/2013; it is neither a general allowance nor an exemption from Swiss withholding tax.
- AVS Rate: 5.3% Employee on Earned Income
- AD/AC rate: 1.1% with maximum CHF 148'200
- LAINF: 0.7-1.5% for nursing care
- LPP: 7–18% depending on age (from 25 years)
- Italian personal income tax: 23% up to €28,000, 33% €28,001-50,000, 43% over €50,000
Swiss direct democracy and federal voting
Switzerland is known for its direct democracy, which allows citizens to actively participate in political decision-making through referendums and popular initiatives. Federal votes are held regularly and involve references to national laws, constitutions, and policies. This unique system has made possible a balance between cantonal autonomy and federal cohesion. For frontier workers, this model translates into specific agreements that regulate taxation and
Operational details
Practical implications for cross-border workers
The New Frontier Agreement, which entered into force on 1 JANUARY 2024, introduced a net replacement for new Italian frontier workers in Switzerland. The latter enjoy a deductible of €10,000, which significantly reduces the initial tax burden. Old cross-border workers remain taxed only in Switzerland (Art. 9 of the 2020 Agreement). This time gap reflects a gradual transition towards more uniform taxation at cantonal level.
Comparison between old and new frontier workers
| Type of border | Exemption/Deductible | Years of validity | Tax impact |
|---|---|---|---|
| Old border | Old cross-border workers remain taxed only in Switzerland (Art. 9 of the 2020 Agreement). | 2024–2033 | Temporary reduction |
| The Article 9 transitional regime applies only to workers who meet the Agreement’s definition and worked in Graubünden, Ticino or Valais between 31 December 2018 and 17 July 2023; covered employment income is taxable exclusively in Switzerland. The ordinary regime applies in other cases, with Italian taxation and credit for Swiss tax where applicable. The €10,000 in Article 4 of Law 83/2023 is only the income limit referred to in Article 1(175) of Law 147/2013, not a general allowance. FTA factsheet · Agreement, Article 9 · Normattiva, Article 4. | — | — | — |
This comparison highlights how Swiss tax policy is adopting a differentiated strategy to better integrate cross-border workers. The exemption for new frontier workers favors entry into Switzerland, while the transitional period for old ones guarantees stability to those who have already established residence.
The role of direct democracy in taxation
The ability to vote and amend laws through cantonal and federal referendums has allowed Switzerland to regularly update its tax system.
Useful planning tools
To estimate your pension strategy, use the pension planner and the pillar 3 simulator.
Key points
How to declare income as a frontier worker in Switzerland
For Italian citizens working in Switzerland, the tax procedure is simplified thanks to the Frontier Agreement. The withholding ONLY takes place in Switzerland, while Italy applies the tax credit to avoid double taxation. Border workers must submit the declaration to the AFC/ESTV, but can take advantage of the Italian tax credit to offset any double taxation.
Tax Return Steps
1. Collect all Swiss tax documents (Payroll, AVS certificates) 2. Submit the declaration to the AFC/ESTV within the established deadlines 3. Apply for the Italian tax credit at the Revenue Agency 4. Keep all correspondence for possible checks
Useful tools for border workers
To accurately calculate taxes and contributions, border workers can use the calcolatore dei redditi on the Frontaliere Ticino website. This tool allows you to simulate gross tax, social security contributions and any Italian tax credit, providing a detailed analysis for each tax component.
Tax deadlines and obligations
Deadlines for filing taxes vary by canton, but generally fall between April and June of the following year. Border workers must also consider the deadlines for the Italian tax credit, which are calculated based on the Italian tax period. In addition, new frontier workers with
Frequently Asked Questions
- What are the tax rates for Italian border workers in Switzerland?
- The rates for Italian border workers in Switzerland include AVS/AI/IPG at 5.3% employee, AD/AC at 1.1% with maximum CHF 148'200, LAINF 0.7-1.5%, and LPP 7–18% by age group (from 25 years). At the Italian level, the IRPEF provides for 23% up to €28,000, 33% for €28,001-50,000 and 43% over €50,000.
- What is the difference between old and new border crossers for tax exemption?
- Old cross-border workers remain taxed only in Switzerland (Art. 9 of the 2020 Agreement). The Article 9 transitional regime applies only to workers who meet the Agreement’s definition and worked in Graubünden, Ticino or Valais between 31 December 2018 and 17 July 2023; covered employment income is taxable exclusively in Switzerland. The ordinary regime applies in other cases, with Italian taxation and credit for Swiss tax where applicable. The €10,000 in Article 4 of Law 83/2023 is only the income limit referred to in Article 1(175) of Law 147/2013, not a general allowance. FTA factsheet · Agreement, Article 9 · Normattiva, Article 4.
- When did the New Frontier Agreement come into force?
- The New Frontier Agreement was signed on 23/12/2020 and is in force from 1 JANUARY 2024, as required by the Italian ratification (Law 83 of 13/6/2023).
- How do you avoid double taxation for border crossers?
- Double taxation is avoided thanks to the Italian tax credit, provided for by the EC framework of 730. Swiss tax is ONLY withheld in Switzerland for resident Italian border workers.
- Which entities should I contact for my tax return?
- For the Swiss declaration please contact the Federal Tax Administration (AFC/ESTV). For the Italian tax credit, on the other hand, contact the Revenue Agency or the MEF.
Related articles
- All articles: Agreements and politics
- Votazioni federali Svizzera: come funzionano e regole
- Votazioni federali: guida al funzionamento della democrazia diretta
- Votazioni federali Svizzera: come funzionano le leggi
- Voto cantonale a Zurigo: iniziative e referendum
- Votazioni Zurigo: alloggi e premi cassa malati al voto